Alternative-financing research
Seller Financing and Owner Financing After Displacement
Understand seller carryback, owner financing, land contracts, balloon payments, title, existing mortgages, servicing, default terms, and fraud risks.
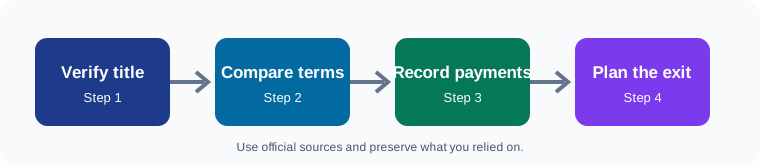
The short answer
Seller financing can describe very different arrangements. The seller may transfer the deed and take a mortgage, retain title under a contract for deed, or propose a transaction involving an existing mortgage. Before signing, identify who holds title, what lien secures the obligation, how payments are credited, whether a balloon is due, and what happens after default.
Terms to put in writing
Verify identity and ownership
Confirm the seller, deed, legal description, taxes, liens, association status, and authority to sell through independent records.
Identify the structure
Determine when title transfers, what document secures payment, who records it, and whether another mortgage remains.
Calculate the real payment
Review price, down payment, interest rate, amortization, balloon date, late charges, taxes, insurance, fees, and prepayment terms.
Plan servicing and records
Use clear statements, receipts, escrow terms where applicable, addresses for notices, and a process for correcting payment errors.
Review default and exit terms
Understand cure periods, acceleration, forfeiture or foreclosure language, sale or refinance rights, and dispute provisions before signing.
Seller-financing comparison
- Independent title and lien search
- Purchase agreement and financing documents reviewed together
- Annual rate, amortization, payment, and balloon date
- Taxes, insurance, repairs, assessments, and recording responsibility
- Existing-loan and due-on-sale questions identified
- Default, notice, cure, payoff, prepayment, and transfer provisions
Print or save this list. Add dates and source information so you can tell what was known at each decision point.
Independent tools and authoritative starting points
CFPB: Help for homeowners
Find current mortgage-help information and ways to contact a housing counselor.
HUD-approved housing counselors
Search for HUD-participating housing counseling agencies.
Legal Services Corporation: Find legal aid
Locate civil legal-aid organizations by address.
FTC: Rental listing scams
Learn how copied listings, fake landlords, and deposit scams operate.
FEMA resilience analysis and planning tool
Compare community-level natural-hazard risk indicators and expected annual loss estimates.
Third-party notice: yPrivateAI is not affiliated with or endorsed by the third-party websites listed here. These links are starting points for independent research. Listings, availability, prices, property descriptions, maps, programs, and terms may change. Verify the property, representative, ownership, title, hazards, insurance availability, and payment instructions independently before making a commitment or transferring funds.
Related Moving On resources
Keep the recovery record together
Preserve notices, estimates, maps, quotes, receipts, listings, and the sources behind each important decision. For related documentation guidance, visit the property-damage documentation checklist and the policyholder resource library.