The Homeowner's Guide to Documenting Property Damage After a Storm
When your home is damaged, the carrier's estimate should not be the only account of your loss. Your photographs, receipts, measurements and correspondence can tell a much more complete story. Build that record from the start so you can identify missing repairs, explain your costs and challenge an estimate with evidence.
After a severe storm, you may be arranging shelter, protecting belongings and answering insurance questions at the same time. A repeatable process helps you keep control. Follow these five steps to turn scattered damage records into a claim file you can actually use.
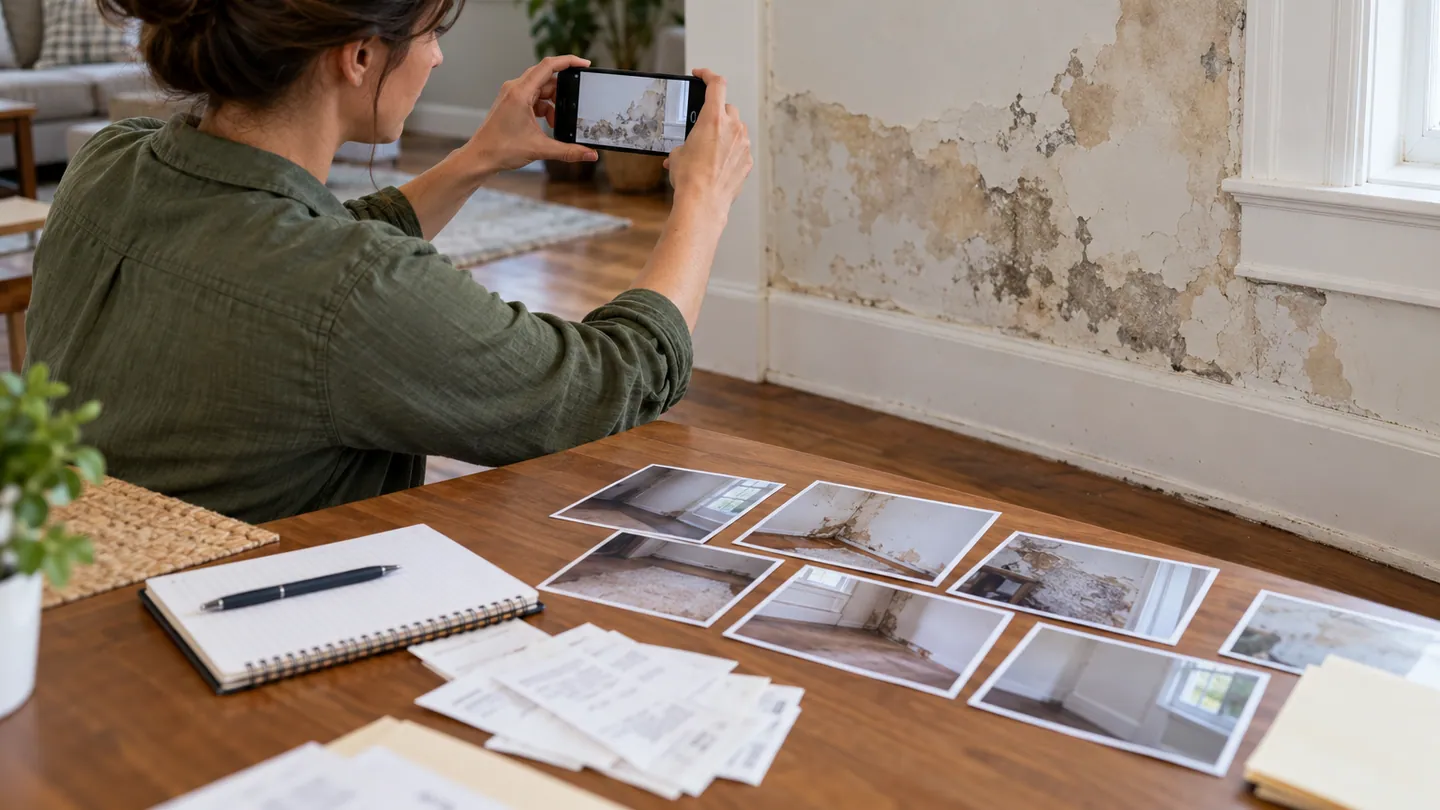
Step 1: Establish Immediate Safety and Prevent Further Damage
Protect people first. Do not enter unsafe buildings, climb a damaged roof or approach fallen power lines to collect evidence. Follow local access restrictions and use qualified help for hazardous work.
Notify your insurer promptly and ask what your policy requires next. When safe, photograph the damage before cleanup and arrange reasonable temporary protection. Keep the emergency work distinct from permanent restoration.
- Document temporary protection. Keep before-and-after photographs of emergency work, the contractor's description and the date it was performed.
- Save mitigation receipts. Retain records for tarps, boarding, emergency labor and other protective work. Reimbursement depends on the covered loss, policy terms and circumstances; a receipt supports the expense but does not establish coverage by itself.
- Coordinate permanent repairs. Contact the insurer before work that removes evidence. Ask how it wants to inspect or document the loss. Do not keep hazardous materials or postpone urgent safety work simply to preserve evidence; document conditions and follow official instructions.
Related: first steps after storm damage and roof tarp safety.
Step 2: Capture Visual Evidence With Context and Detail
Show where the damage is, what it looks like and which item it affects. Work through each safely accessible area in a consistent order. Keep original files and use separate copies for arrows, labels or other annotations.
- Start wide. Photograph the room or exterior elevation before moving closer. Include adjoining surfaces so a reviewer can locate the damage.
- Then capture specifics. Record water lines, broken materials, displaced components and visible impact marks. Describe what you observe without guessing at hidden damage or its cause.
- Add a scale where safe. Include a ruler or tape measure without disturbing the damage. Pair the detail image with a wider photograph.
- Record identifying labels. Capture model and serial numbers on damaged appliances or electronics when accessible.
- Make a photo index. Use file references such as P001 and P002, with the room, date and a short description. Link those references to inventory items or estimate questions.
A narrated video walkthrough can add context. Photographs are valuable, but other records can also support a loss if a photograph is unavailable.
Step 3: Build a Room-by-Room Damaged Property Inventory
List items individually while the details are fresh. Use past photographs, purchase histories and other records to fill gaps, and identify uncertain figures as estimates.
- Item and location: description, brand, model, quantity and room.
- Age and pre-loss condition: purchase date if known, or a clearly marked approximation.
- Ownership and value records: receipts, order confirmations or relevant payment records.
- Replacement research: a dated price and source for the same item or a reasonable current equivalent. Explain meaningful differences.
- Evidence references: connect the item to its photographs, receipt and any inspection record.
Keep original purchase cost separate from estimated replacement cost and any amount the insurer allows. Your policy determines how valuation, depreciation, deductibles and limits apply.
Use the receipt organization and claim documentation checklist.
Step 4: Maintain a Chronological Communication Timeline
When the claim stalls, be ready to show the sequence. A dated record helps distinguish a missing document from an unanswered request and lets you prepare a specific follow-up.
- Log each conversation. Record the date, time, contact details, representative's name, subjects discussed and any stated next step.
- Confirm your understanding in writing. After a call, send a short factual summary and invite corrections. Save the message and any reply.
- Track submissions. Note what you sent, the version, delivery method and confirmation. Keep the submitted packet intact.
- Record milestones. Include the report of loss, inspections, estimates, information requests, decisions and payments. Confirm applicable deadlines rather than assuming one rule applies everywhere.
Example follow-up: “Following our call today, I understand the inspection is scheduled for Thursday. Please confirm the appointment and let me know if you need any documents beforehand.”
Keep notes as notes and distinguish them from the carrier's actual words. If a handling concern remains unresolved, prepare a documented insurance complaint.
Step 5: Secure Independent Estimates and Compare the Details
A competing total is less useful than a clear explanation of the difference. Obtain written, itemized estimates from qualified contractors and check credentials, licensing requirements and references.
- Ask for a defined scope. Identify the location, work, materials, quantities and labor supporting the proposed repair.
- Separate restoration from optional upgrades. Identify proposed improvements, code-related work and other differences explicitly so they can be reviewed against the policy.
- Compare line by line. Mark missing tasks, different quantities or materials, and pricing differences. Connect each question to a photograph, measurement, contractor explanation or price source.
- Keep versions and payment records. Preserve earlier estimates and record what changed. An estimate, an agreed amount and an actual payment are different records.
See how to compare your estimate with the carrier's estimate, or prepare your next step after a denial or underpayment.
Turn Your Documentation Into a Stronger Claim With PAi Claims
You have the photographs. You have the receipts. Now put them to work. PAi Claims connects your evidence, independent repair estimate, carrier comparison and claim history in one Windows workspace. Stop rebuilding the story from scattered folders every time someone asks for another document.
Use AI to analyze correspondence, examine policy language and draft summaries from your record. Choose a compatible local AI model to process those operations on your computer without sending their content to a hosted AI provider. Workspace folders are yours to choose; cloud-synced storage follows its service's terms. Optional external AI and connected lookups send the information needed for those requests under the relevant provider's terms.
Build your estimate. Document the differences. Prepare your response. Download and setup are free; creating the first claim is $20. Existing claims remain available to open, work on and export. Purchases help sustain NFCcop's services and free recovery resources.
Download PAi Claims Free — Start Building Your Claim
Explore the full PAi Claims workflow · Review pricing · Request free-access assistance
On a phone? Use this guide now, save your original photos and receipts, and open PAi Claims later on Windows 10 or 11. No installation is required to read these steps.
Sources and Further Claim Guidance
Reviewed November 4, 2026. This is general documentation guidance. Coverage, payment, policy duties and deadlines depend on the policy, loss and applicable rules.
- NAIC: documenting losses, reporting claims and temporary repairs.
- NFIP: visual damage records, samples, receipts and repair services. Flood-policy guidance is specific to flood claims.
- NFIP policyholder checklist: inventory details and estimate review.
- New York DFS: claim records, written follow-up, contractor estimates and repair coordination. State-specific guidance; check your own jurisdiction.