Mortgage Forbearance: Meaning, Options, and What Happens Next
Understand mortgage forbearance, questions to ask a servicer, records to keep, post-forbearance possibilities, foreclosure risk, and relief scams.
A structured starting point. Verify details for the exact household, loan, jurisdiction, and property.
The short answer
Mortgage forbearance generally means a servicer permits a temporary pause or reduction in required payments. It usually does not erase the amount that was not paid. The exact agreement, repayment path, interest, escrow treatment, credit reporting, and available next steps depend on the loan, investor, program, and written terms.
A careful housing search considers cost, location, safety, and the reliability of every listing.
Before agreeing to forbearance
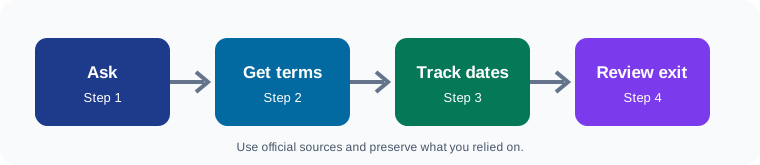
Verify the servicer
Use the number on a recent statement or the servicer’s independently located official website—not a number in an unsolicited message.
Describe the hardship
Explain the disaster, income interruption, displacement, repair obligations, and the time frame you can document.
Ask for written terms
Request the start and end dates, payment amount, interest and fee treatment, escrow handling, credit-reporting information, and exit options.
Calendar follow-ups
Record confirmation numbers and schedule contact well before the forbearance period ends.
Review the exit
Ask what evaluation or documents are required for repayment, deferral, modification, reinstatement, sale, or another available option.
Servicer conversation log
Date, time, telephone number, and representative name or ID
Hardship description and documents requested
Quoted payment, dates, fees, interest, and escrow terms
Confirmation or case number
Written agreement received and saved
Next deadline and next scheduled contact
Print or save this list. Add dates and source information so you can tell what was known at each decision point.
Comparing policy language, damage evidence, and estimates can reveal questions that need follow-up.
Independent tools and authoritative starting points
Third-party notice: yPrivateAI is not affiliated with or endorsed by the third-party websites listed here. These links are starting points for independent research. Listings, availability, prices, property descriptions, maps, programs, and terms may change. Verify the property, representative, ownership, title, hazards, insurance availability, and payment instructions independently before making a commitment or transferring funds.
A practical guide to replacement-home research after a fire, flood, hurricane, or other total loss, including hazards, insurance, listings, and documentation.
How do I request mortgage forbearance after a disaster?
Contact your mortgage servicer through a verified channel, explain the hardship, and ask what options apply to your loan. Request the terms and any deadlines in writing.
What should I ask my mortgage servicer about forbearance?
Ask about payment amounts, start and end dates, interest, fees, escrow, credit reporting, and repayment or exit options. Keep a written record of the conversation and agreement.
Does mortgage forbearance erase missed payments?
No. A payment pause or reduction does not cancel the amounts owed. The repayment arrangement depends on the loan, program, and written agreement with the servicer.
What happens when mortgage forbearance ends?
Contact the servicer before the end date to discuss the applicable repayment or other available options. Do not assume that every loan offers the same exit arrangement.
What records should I keep during mortgage forbearance?
Save hardship documents, statements, written terms, representative details, confirmation numbers, and submission records. Maintain a calendar for the end date, requested documents, and follow-up contacts.
How do I recognize mortgage relief scams?
Watch for guaranteed outcomes, advance-fee demands, instructions to stop contacting your real servicer, or pressure to transfer a deed. Verify the organization independently before sharing records or money.
Where can I find a housing counselor?
Use the official HUD-approved housing-counselor directory linked in this guide. Confirm the agency and explain your mortgage problem, deadlines, and any written notices you received.
Does NFCcop arrange mortgage payment pauses?
No. This is an educational guide. Your mortgage servicer determines available arrangements for your loan; qualified housing counselors and legal-aid providers may help you explore options.
Use the sources and official referral links in this guide to verify current information. NFCcop provides educational resources, not emergency dispatch, claim representation, legal representation, mortgage servicing, or guaranteed assistance.