Flood Insurance Basics
Last reviewed November 6, 2026. Free public guidance from The New Faith Church and Co-op, Inc. (NFCcop), a 501(c)(3) nonprofit. This is general information, not legal or professional advice. Rules and deadlines can change, so confirm with the official sources below.
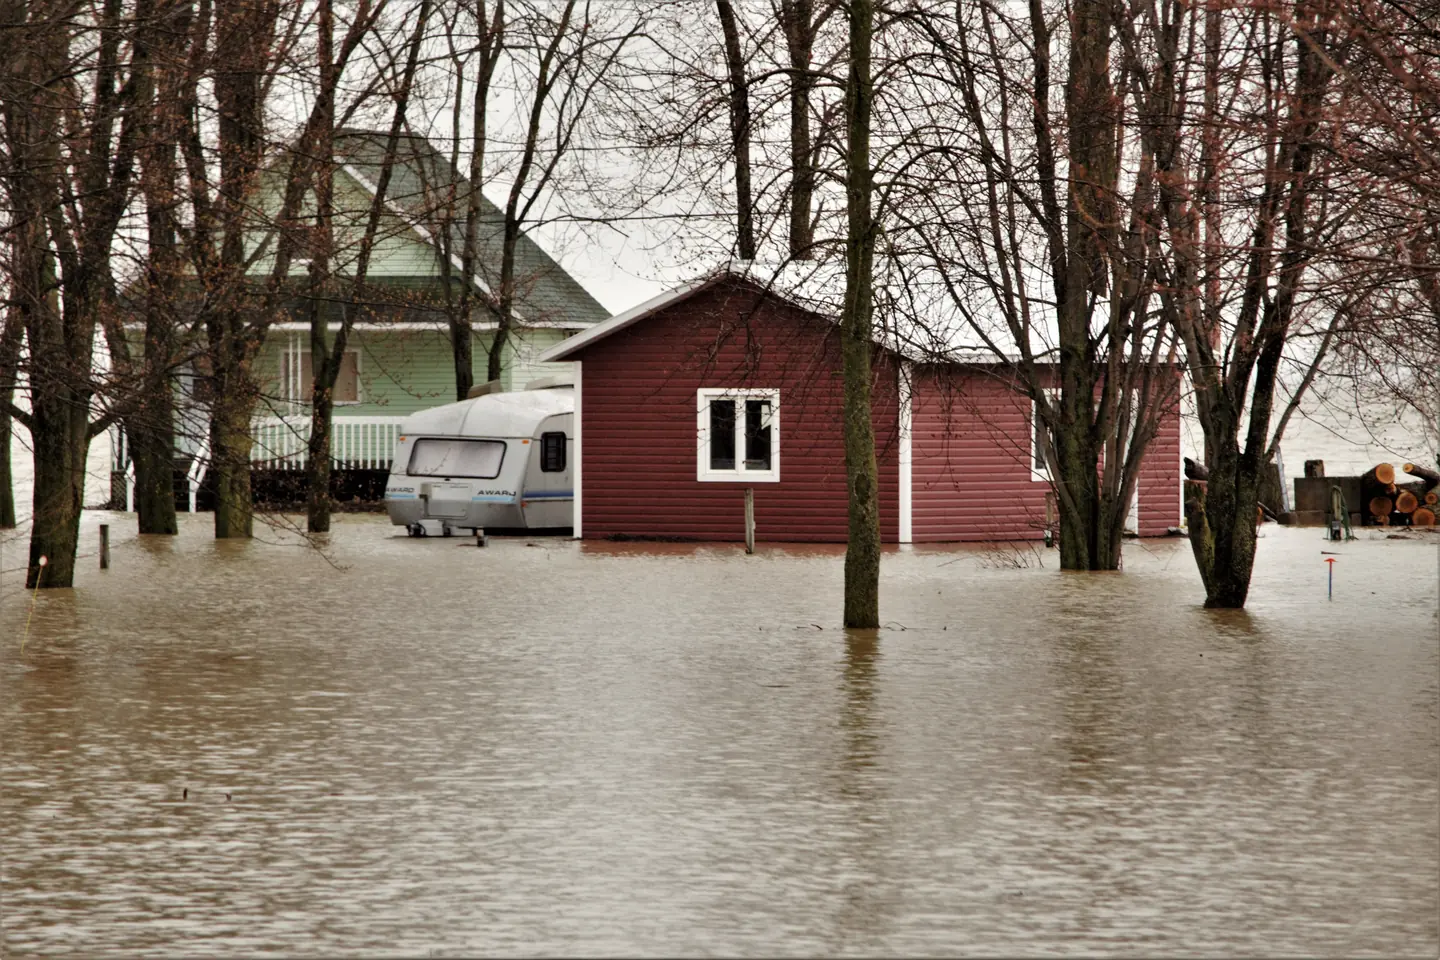
Most homeowners and renters insurance policies do not cover flood damage. Flood insurance is a separate policy. Floods can happen anywhere, including outside high-risk flood zones, so it's worth understanding before the next storm.
Two kinds of coverage
- Building coverage pays to repair the structure: foundation, walls, floors, electrical and plumbing, furnace, water heater, and built-in appliances.
- Contents coverage pays for your belongings, like furniture, clothing, and electronics. Renters can buy contents coverage on its own.
Most flood insurance is sold through the National Flood Insurance Program (NFIP), run by FEMA, through regular insurance agents. Private flood insurance is also available in many areas.
The 30-day waiting period
NFIP policies typically take 30 days to go into effect. Exceptions include coverage required by a lender when you buy or refinance a home. A policy bought when a storm is already coming usually won't cover that storm, so buy it well ahead of hurricane season.
What flood insurance usually doesn't cover
- Temporary housing or additional living expenses
- Cars and other vehicles; those are covered by auto comprehensive coverage. See car flood damage.
- Most property outside the building, like fences, decks, and landscaping
- Damage from mold or moisture that the owner could have prevented
- Many items in basements are limited
Read your policy for details, and ask your agent about coverage limits.
Find your flood risk
Check your address on FEMA's flood maps and learn your zone. Our flood zone research guide walks you through it. Even in a low-risk zone, flood insurance is often much cheaper.
If you flood
- Make sure it's safe to go back in.
- Photograph and video all damage before cleaning, and keep samples of materials like carpet.
- Report the claim to your flood insurer as soon as possible.
- Start cleanup to prevent mold. See flood cleanup and mold after a flood.
No flood insurance?
After a declared disaster, you may be able to get FEMA assistance and SBA disaster loans. These usually cover far less than insurance would.
Frequently asked questions
Does homeowners insurance cover flooding?
Usually not. Flood damage from rising water is covered by a separate flood insurance policy, through the NFIP or a private insurer.
How long does flood insurance take to start?
NFIP policies typically have a 30-day waiting period, with exceptions such as coverage required by a lender when you buy or refinance a home.
Can renters buy flood insurance?
Yes. Renters can buy contents-only flood insurance to cover their belongings.
Need help with your claim or paperwork?
NFCcop offers free guidance to storm survivors. Ask for free help or browse all disaster recovery resources.