Wind vs. Flood Damage: Which Policy Pays?
Last reviewed November 10, 2026. Free public guidance from The New Faith Church and Co-op, Inc. (NFCcop), a 501(c)(3) nonprofit. This is general information, not legal or professional advice. Rules and deadlines can change, so confirm with the official sources below.
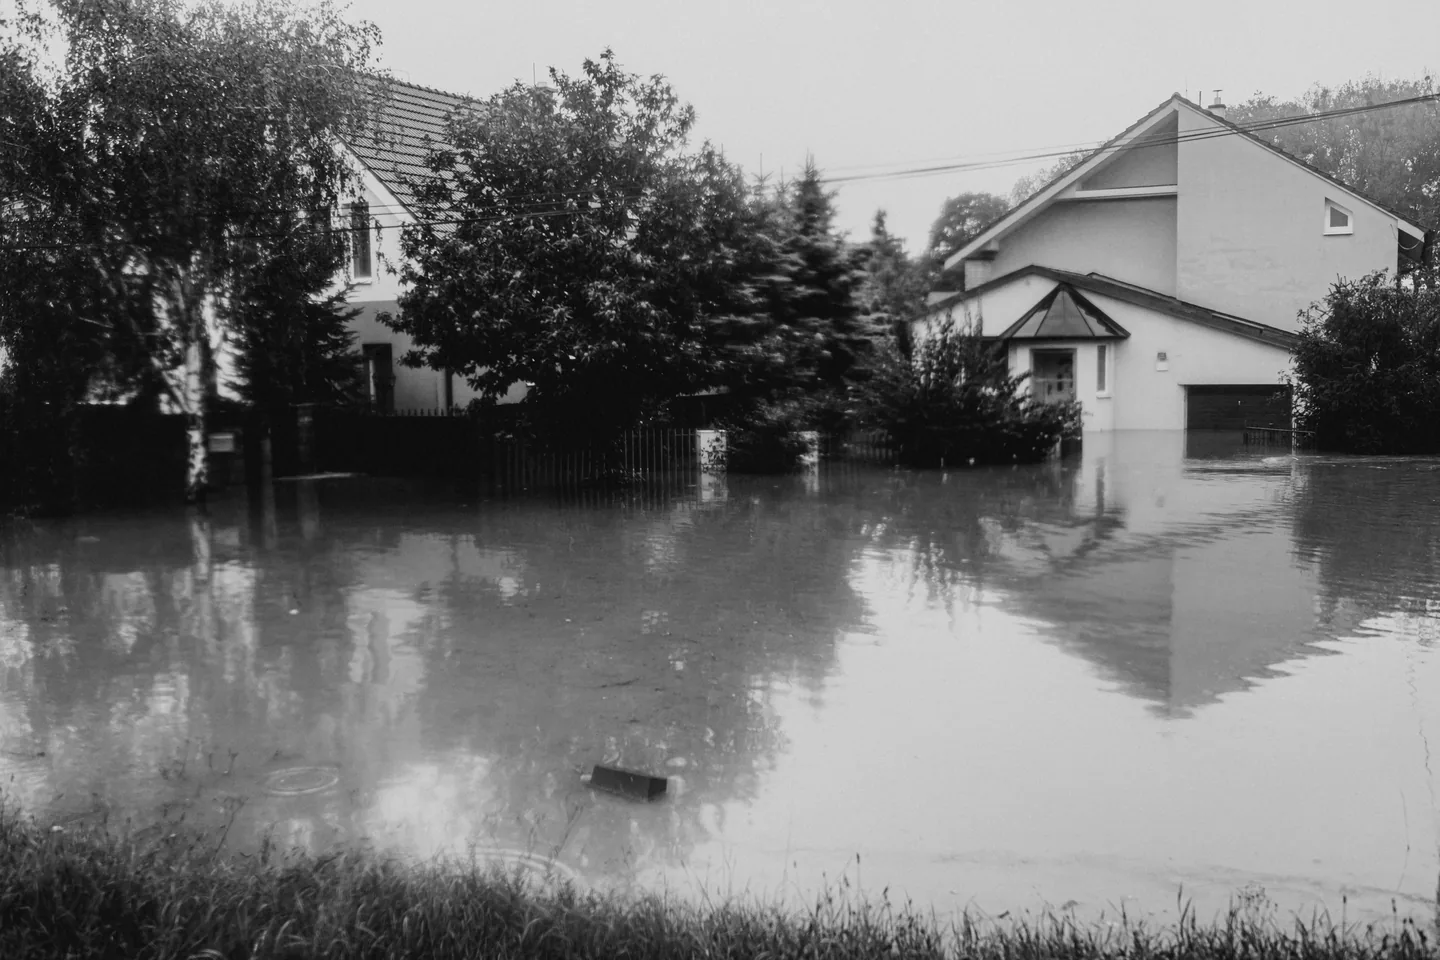
After a hurricane, many homes have both wind damage and flood damage. They're usually covered by different policies, and the difference can decide whether you get paid. Standard homeowners policies cover wind but generally exclude flood, including storm surge.
Who covers what
| Damage | Usually covered by |
|---|---|
| Wind tears off shingles or siding | Homeowners policy (may have a separate hurricane or wind deductible) |
| Rain enters through a hole the wind made | Homeowners policy |
| Storm surge or rising water floods the house | Flood insurance (NFIP or private flood) |
| Rain seeps in with no storm opening | Often excluded. Check your policy |
| Sewer or drain backup | Often needs a separate endorsement |
In some coastal areas, wind is covered by a separate wind pool or windstorm policy instead of the homeowners policy.
File both claims if you have both kinds of damage
- File with your homeowners (or wind) insurer and your flood insurer. Don't wait for one to finish before starting the other.
- Tell each adjuster about the other claim.
- For flood, you'll usually need a signed proof of loss.
Document what caused what
- Photograph the water line on walls, inside and out, and measure it.
- Photograph roof, window, and siding damage separately.
- Keep news reports or local data on surge height and wind speeds in your area.
- Note the order of events if you know it, for example "roof was torn off before the water came in."
If one insurer blames the other
Insurers sometimes argue damage was caused by the peril the other policy covers. Ask each for a written explanation, send your evidence, and file a free complaint with your state insurance department if needed. See claim denied.
No flood insurance? FEMA may help with basic repairs not covered by insurance. See the FEMA application guide and flood insurance basics.
Frequently asked questions
Does homeowners insurance cover storm surge?
Usually not. Storm surge is generally treated as flood, which most homeowners policies exclude. Flood insurance covers it.
Can I file wind and flood claims at the same time?
Yes. If you have both kinds of damage, file with both insurers right away and tell each adjuster about the other claim.
What is a hurricane deductible?
A separate deductible for hurricane or wind damage, often a percentage of your home's insured value instead of a flat dollar amount. Check your declarations page.
Need help with your claim or paperwork?
NFCcop offers free guidance to storm survivors. Ask for free help or browse all disaster recovery resources.